Expat mortgage calculator
How much could you borrow on foreign income?
Sterling income takes no reduction. Everything else is converted and then reduced by 15% to 25% for exchange-rate movement.
1 EUR = £0.86. Rates shown are the published spot rates, checked October 2026. A lender uses its own rate on the day, which will differ.
What are you buying?Your country of residence changes which lenders can look at your case
Present in the UK for fewer than 183 days in the 12 months before the purchase.
- Income a lender would assess
- £45,150 £51,170
- Deposit at around 25%
- £75,000
- Loan the property would need
- £225,000
- Loan-to-value
- 75%
- Monthly payment on the £225,000 loan this property needs
- £1,315
A repayment mortgage over the term you set. Interest-only would be lower, and leaves the capital outstanding.
Within reach at the upper end of the range
The loan this property needs falls inside the range rather than below it. Whether it works depends on which lender looks at the case and how that lender treats your income — some would lend this much on these figures and some would not. It is worth a conversation before you rule it out.
Measured against the property value you entered, less a deposit of around 25%.
Illustrative only — not an offer or a quote, and it depends on your circumstances. Lender criteria checked October 2026.
Find out where you standWhy foreign income is treated differently
A lender does not lend against your salary as you receive it. It converts, reduces, and then applies a multiple to what is left. Each step is shown below with your own figures in it.
- What you earn€70,000In the currency you are paid in
- Converted to sterling£60,200At the published spot rate
- Reduced by 15% to 25%£45,150 – £51,170The allowance a lender makes for the exchange rate moving against it over the life of the loan
- Multiplied by 4 to 4.5£180,600 – £230,265The income multiple a lender works to
Total cash needed upfront
The deposit is not the whole of it. This adds the stamp duty and our fee so the figure you plan around is the one you actually need on the day.
- Deposit at around 25%
- £75,000
- Stamp Duty Land Tax
- £11,000
- Our fee
- £495
- Cash needed upfront
- £86,495
A buyer who is not UK resident pays a surcharge of 2 percentage points on every band, per GOV.UK, read October 2026. GOV.UK. England and Northern Ireland only. Scotland charges Land and Buildings Transaction Tax and Wales charges Land Transaction Tax, both on their own thresholds — tell us where the property is and we will work it out properly. It excludes conveyancing, survey, lender product fees and any currency transfer cost.
Our standard fee is £495, payable when your application is submitted. In some more complex cases, an additional broker fee of up to 1% of the loan may apply. The first conversation is always free, and we always confirm your total fee in writing before any work starts.
What your country of residence changes
- EuropeA well-served region. Euro income is widely accepted and several specialist lenders are active across the EU, including for clients on the Costa del Sol.
- DepositExpat deposits are usually around 25%, and some lenders will consider less for the right profile.
- UK credit fileA thin UK credit file is expected and does not end the case. Specialist lenders look at the wider picture — overseas bank statements, your employment, your deposit, and any UK accounts you have kept open.
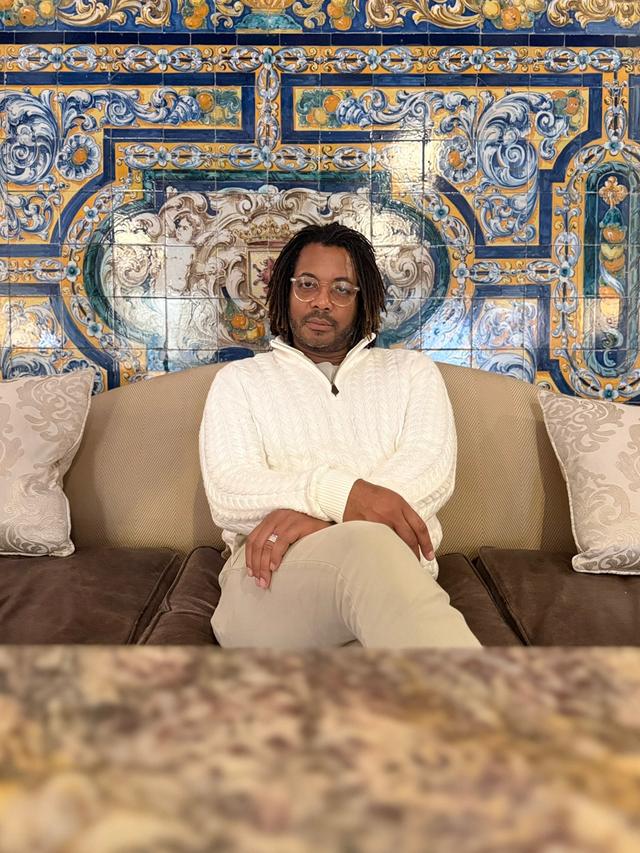
Want me to check this against real lenders? I'll tell you which ones would look at your case.
Nathan Lawes · Director & Mortgage Adviser
No credit check · no obligation
Keep your copy
We'll send this to your inbox — no spam, no obligation.
Roughly four to four and a half times your income — but a lender converts your overseas pay into sterling first and then reduces it, typically by 15% to 25%, to allow for exchange-rate movement. That reduction is why expat borrowing comes out lower than the same salary earned in the UK.
Set your income, currency and the property you have in mind. The result shows a range rather than a single figure, because the lenders that consider overseas income do not all treat it the same way.
How this calculator works
- 01
Convert
Your income is converted to sterling at the published spot rate, checked October 2026. A lender will use its own rate on the day of the application, and it is usually a more conservative one.
- 02
Reduce by 15% to 25%
Lenders reduce converted foreign income by about 15% to 25% to allow for the exchange rate moving. Sterling income is not reduced. This single step is the main reason expat borrowing is lower than the same salary earned in the UK.
- 03
Multiply by 4 to 4.5
The reduced figure is multiplied by an income multiple of around 4 to 4.5 times. The range is the point: lenders differ, and a single number would read as a quote.
- 04
Compare with the deposit
The result is set against the property value you entered, less a deposit of around 25%, to show whether the borrowing reaches what the purchase would need.
These are general criteria, not the terms of any one lender, and not a recommendation.
The same salary, three currencies
Each row is the same arithmetic the tool runs: convert at the rate shown, reduce by 15% to 25%, then multiply by 4 to 4.5.
| Income | Rate used | In sterling | Assessed range | Borrowing range |
|---|---|---|---|---|
| €120,000 | £0.86 | £103,200 | £77,400 – £87,720 | £309,600 – £394,740 |
| $150,000 | £0.757 | £113,550 | £85,163 – £96,518 | £340,650 – £434,329 |
| AED 450,000 | £0.206 | £92,700 | £69,525 – £78,795 | £278,100 – £354,578 |
Illustrative, and it depends on your circumstances. Rates checked October 2026; lender criteria are general and are not the terms of any one lender.
What are expat mortgage rates like?
Pricing for an expat mortgage is often higher than for a UK resident borrowing the same amount, and the gap varies by lender rather than being a fixed premium. We do not publish rates on this site, because the rate you are offered depends on the case rather than on the category.
How much you are borrowing against the property
Loan-to-value moves the price more than anything else on this list. A larger deposit reaches better pricing tiers, which is one practical reason the deposit question is worth revisiting before you fix on a property.
The currency you are paid in
Widely accepted currencies reach more lenders, and more lenders competing for a case tends to show up in the price. A less common currency narrows the panel before pricing is even discussed.
Where you live, and your residency status
Country of residence decides which lenders can consider the case at all. Some jurisdictions carry reporting obligations that certain lenders would rather not take on.
How much appetite a lender has that month
Specialist lending capacity moves. A lender that was keen on overseas cases in the spring may have filled its book by the autumn, and the panel that suited a case three months ago may not be the right one now.
What happens next
There is no fee until the application stage. Our standard fee is £495, payable when your application is submitted. In some more complex cases, an additional broker fee of up to 1% of the loan may apply. The first conversation is always free, and we always confirm your total fee in writing before any work starts.
Wherever you are, we work to your clock
- London
- Madrid
- Dubai
- Singapore
- Hong Kong
- New York
Calls are arranged around your time zone, not ours. Everything is done remotely — video calls, e-signing, documents uploaded from wherever you are.
Expat buy-to-let: the rent a lender needs to see
A buy-to-let lender does not start with your salary. It starts with the rent, tests it against the interest on the loan, and lends what that test supports. For an expat the currency reduction still applies to any income a lender does consider, but the rent is what decides the loan.
How much rent does a buy-to-let lender need to see?
Enough to cover the interest on the loan at a stress rate, by a margin. Lenders commonly test at a 5.5% stress rate rather than the rate you would pay, and ask for rental cover of 125% to 145% of that interest.
What does that look like on a real purchase?
Take a £300,000 property bought with a deposit of 25%, which leaves a loan of £225,000.
At a 5.5% stress rate the interest on that loan is £12,375 a year. Rental cover of 125% means a lender wants to see about £1,289 a month; rental cover of 145% means about £1,495 a month.
Illustrative, and it depends on your circumstances. These are general criteria, not the terms of any one lender, and not a recommendation.
What if the rent falls short?
Some lenders will also take your personal income into account where the rent falls short — often called top-slicing. Whether it's available depends on the lender and your income, and it is one of the questions worth settling before an application is made rather than after.
Does buying as a non-resident change the stamp duty?
Yes, twice over. A let property usually attracts the higher rates for additional dwellings — for example if you already own a home anywhere in the world, or buy through a company — and a buyer who is not UK resident pays a further surcharge of 2 percentage points on every band, per GOV.UK, read October 2026. The calculator above adds both to the cash you would need upfront. GOV.UK.
Already buying in Spain?
Nathan splits his time between London and Spain. Euro income, Spanish payslips and a UK purchase is a combination we know well.
Questions about the numbers
How much can I borrow on a UK mortgage if I am paid in a foreign currency?
As a rule of thumb, around 4 to 4.5 times the income a lender assesses — but for foreign income that is not the figure on your payslip. A lender converts your income to sterling at its own rate, then reduces it by about 15% to 25% to allow for the exchange rate moving over the life of the loan, and applies the multiple to what is left.
So a salary that would support £450,000 of borrowing if it were paid in sterling might support closer to £340,000 to £380,000 paid in euros. The calculator on this page shows the whole chain with your own figures in it.
Why is the number lower than a normal mortgage calculator gives me?
Because an ordinary affordability calculator assumes sterling income and applies the multiple directly. This one applies the currency reduction first, which is what a specialist lender actually does.
It also shows a range rather than a single figure. Lenders differ on both the reduction and the multiple, and quoting one number would imply a precision that does not exist before a lender has seen the case.
What exchange rate does the calculator use?
The published spot rate, checked October 2026. Sterling, euro, US dollar, Singapore dollar and Hong Kong dollar rates come from the Bank of England's daily spot series; the dirham rate comes from the UAE Central Bank, because the Bank of England publishes no dirham series.
A lender will use its own rate on the day of the application, and it is usually a more conservative one than the market rate. That is a separate thing from the 15% to 25% reduction, which is applied after the conversion.
What deposit do I need as an expat buyer?
Expat deposits are usually around 25%, and some lenders will consider less for the right profile. The deposit is the single biggest practical difference between expat lending and resident lending.
A larger deposit does more than clear the minimum — it reaches better pricing tiers, and it widens the panel of lenders that will look at the case at all.
Does the calculator include stamp duty?
Yes. The cash-needed-upfront figure adds Stamp Duty Land Tax to the deposit and our fee, and there is a toggle for the non-resident surcharge of 2 percentage points that applies if you were not present in the UK for at least 183 days in the 12 months before the purchase. Source: GOV.UK, Rates of Stamp Duty Land Tax for non-UK residents, read October 2026.
It covers England and Northern Ireland only. Scotland charges Land and Buildings Transaction Tax and Wales charges Land Transaction Tax, both on their own thresholds. It also excludes conveyancing, survey and lender product fees.
Can I use this for a buy-to-let?
Yes — switch the purchase type to a property to let, and the calculator shows the rent a lender would need to see rather than leaning on your income.
A buy-to-let lender tests the rent against the interest on the loan at a stress rate rather than the rate you pay, commonly 5.5%, and asks for rental cover of 125% to 145%. In a great many landlord cases those two numbers decide the loan long before income does.
What are expat mortgage rates like?
Pricing is often higher than for a UK resident borrowing the same amount, and the gap varies by lender rather than being a fixed premium. We do not publish rates, because the rate you are offered depends on the case rather than the category.
What moves it: how much you are borrowing against the property, the currency you are paid in, where you live and your residency status, and how much appetite a given lender has for overseas cases that month. For published market data, our rates page carries the Bank of England's monthly averages — those are market figures, not our rates and not a quote.
Will a thin UK credit file stop me borrowing?
Not necessarily. A thin UK credit file is expected and does not end the case. Specialist lenders that work with expats and foreign nationals look at the wider picture instead — your overseas bank statements, your employment, your deposit, and any UK accounts you have kept open.
A UK bank account or an old UK address still on file helps, but their absence does not end the case.
Is this an offer or a decision in principle?
Neither. It is an illustration built from the figures you entered and general criteria checked October 2026 — not an offer, not a quote, and not the terms of any one lender.
A decision in principle comes from a lender after it has seen your case. Nothing on this page runs a credit check or contacts a lender.
Do I need to come to the UK to apply?
No. The whole process runs remotely — video calls arranged around your time zone, documents uploaded, and e-signing where the lender supports it.
A small number of lenders still want a signature witnessed in person at the legal stage, and where that is the case we tell you at the outset rather than at the end.
What will you ask me for?
Your passport and your visa or residence permit where one applies, proof of your address abroad, three to six months of payslips, overseas bank statements showing the salary arriving, and your employment contract — or two to three years of accounts if you are self-employed. Certified translations are needed where a document is not in English.
The list varies by lender and by income type, so we send you a checklist written for your case rather than a generic one.
What does your advice cost?
Our standard fee is £495, payable when your application is submitted. In some more complex cases, an additional broker fee of up to 1% of the loan may apply. The first conversation is always free, and we always confirm your total fee in writing before any work starts.
There is no fee until the application stage, so working out whether a case is viable costs you nothing.
Find out where you stand
A calculator works from four numbers. A lender works from your whole case — the currency, the country, the employment, the deposit and the credit file. Tell us the case and we will tell you which lenders would look at it.
Appointed representative · FRN 1046161 · Whole-of-market · Independent advice
Your home or property may be repossessed if you do not keep up repayments on a mortgage or any other debt secured on it.
Your home or property may be repossessed if you do not keep up repayments on a mortgage or any other debt secured on it.